As an investor, understanding the actual performance of your investments is crucial for making informed decisions. Simply seeing an asset's value increase is not enough; you must know how to calculate financial return accurately. This article is your essential guide to achieving that.
Financial return calculation allows for the evaluation of an investment's real performance. It is crucial to look beyond simple ROI by integrating factors such as time and taxation, using tools like IRR, for optimal management of your investment portfolio.
Calculating Financial Return: Your Complete Investor Guide
1. Why is financial return calculation indispensable?
Maximizing gains and minimizing risks is the goal of every savvy investor. To achieve this, a deep understanding of financial return calculation is required. It is not just a matter of final figures, but also knowing how those figures are obtained and what they mean for the future of your portfolio. Ignoring this step can lead to costly investment errors and chronic underperformance. An accurate calculation allows you to compare disparate investment opportunities, evaluate the effectiveness of your strategies, and adjust your approach accordingly. It is the pillar of sound, non-emotional decision-making.
2. Investment ROI: An essential but imperfect first step
Simple investment ROI calculation, or Return on Investment, is often the first metric investors consider. It is a basic, easy-to-understand performance indicator that measures the profit or loss generated relative to the initial cost of an investment.
How to calculate simple ROI?
The formula is as follows:
(Investment Gain - Investment Cost) / Investment Cost
- Example: You buy a stock at €100 and sell it for €120. Your ROI is (€120 - €100) / €100 = 0.20, or 20%. However, ROI has its limits. It does not take into account the duration of the investment, which makes comparing projects of different lengths difficult. A 20% ROI over 6 months is much higher performing than the same ROI over 5 years. This is why other indicators are necessary.
3. Internal Rate of Return (IRR): Integrating the time dimension
The internal rate of return (IRR) is a much more sophisticated tool, particularly relevant for investments with multiple cash flows spread over time. The IRR represents the discount rate that makes the net present value (NPV) of all cash flows (positive and negative) equal to zero. In other words, it is the rate that equates the initial investment amount with the discounted sum of future flows generated by that investment. In practical terms, a high IRR indicates a potentially profitable investment. It allows for the comparison of the average annual profitability of investments, regardless of their duration or cash flow patterns.
- Advantages of IRR:
- Accounts for the time value of money.
- Ideal for long-term investment projects with variable cash flows.
- Allows for a fairer comparison between different projects. Its calculation complexity often requires the use of financial software or spreadsheets (Excel, Google Sheets).
4. Investment Multiples and Equity Valuation
Beyond pure profitability calculations, equity investment multiples are financial ratios that help investors evaluate the relative value of a company or asset compared to others. They are particularly used in the context of stock market investing.
- Examples of multiples:
- PER (Price-to-Earnings Ratio): Stock price / Earnings per share. Indicates how much investors are willing to pay for each euro of profit.
- P/B (Price-to-Book Ratio): Stock price / Book value per share. Compares the market price of a stock to its book value.
- EV/EBITDA (Enterprise Value-to-EBITDA): Enterprise value / Earnings before interest, taxes, depreciation, and amortization. Often used to evaluate companies with different debt levels. These multiples help determine if a company is overvalued or undervalued relative to its peers or sector. They are a pillar of the financial portfolio performance guide for investors seeking growth.
5. Financial Portfolio Performance: Going beyond raw numbers
The financial portfolio performance guide is a holistic approach that encompasses not only the individual returns of each asset but also the impact of diversification, management fees, and taxation. A well-constructed portfolio does more than just hold good assets; it optimizes their synergy and minimizes capital leakage.
- Factors to consider for overall performance:
- Fees: Management fees, brokerage fees, entry/exit loads. These eat away at a portion of your return.
- Taxation: Taxes on capital gains and investment income reduce your net return. An optimized tax strategy is essential.
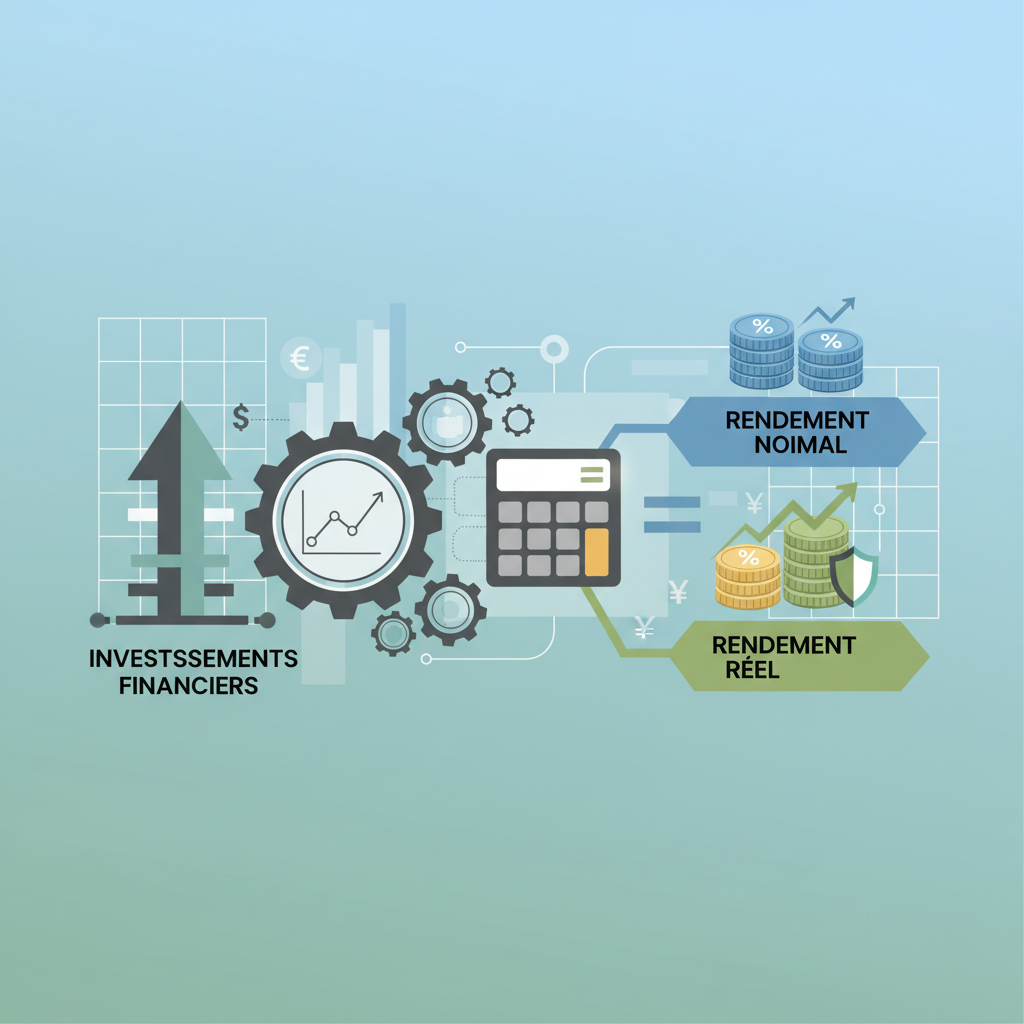
- Inflation: The "real" return is the nominal return minus the inflation rate. This is crucial for maintaining your purchasing power.
6. Tools and Best Practices for Accurate Calculation
For a reliable financial return calculation, several tools and best practices are at your disposal:
- Spreadsheets (Excel, Google Sheets): Indispensable for IRR and NPV calculations and scenario modeling.
- Brokerage Platforms: Most offer performance history and analysis tools for your portfolio.
- Wealth Management Software: For more complex portfolios, these offer a consolidated view and in-depth analysis. Best Practices:
- Consistency: Use the same methodologies and time periods to compare investments.
- Realism: Always integrate fees and taxes into your calculations.
- Monitoring: Stay updated on market tools and indicators.
| Criterion | Comparative Advantage | Complexity Level |
|---|---|---|
| Simple ROI | Quick and easy | Low |
| Internal Rate of Return (IRR) | Prioritizes timing | Medium to High |
| Valuation Multiples | Sector comparison | Medium |
| Net Return (post-fees/tax) | Reflects real performance | Medium |
- Ignoring hidden fees: Certain management or platform fees can significantly impact net return without being immediately apparent.
- Neglecting inflation: A high nominal return can be disappointing once inflation is factored in, eroding purchasing power.
- Comparing apples to oranges: Poor comparisons between investments of different durations, risks, or structures lead to erroneous conclusions.
- Audit your portfolio: List all your investments with their acquisition costs, current values, and associated cash flows.
- Calculate simple ROI: Perform an initial pass for each investment to get a quick overview.
- Apply IRR or other metrics: Use a spreadsheet for long-term investments or those with multiple flows.
- Integrate fees and taxes: Estimate your net return after all deductions to obtain the real performance.
- Autorité des Marchés Financiers (AMF) | https://www.amf-france.org/
- Investopedia | https://www.investopedia.com/
What is the difference between nominal return and real return? Nominal return is the gross return before any deductions. Real return is the nominal return adjusted for inflation, providing a better measure of the increase in purchasing power. Is IRR always the best performance indicator? IRR is an excellent indicator for many investments, but it can have limitations in complex cases (highly alternating positive and negative cash flows) where NPV (Net Present Value) is a preferable complement. How does taxation impact my return? Taxation reduces your net return. It is crucial to integrate taxes on capital gains, dividends, or rental income into your calculations to get an accurate picture of your actual gain.